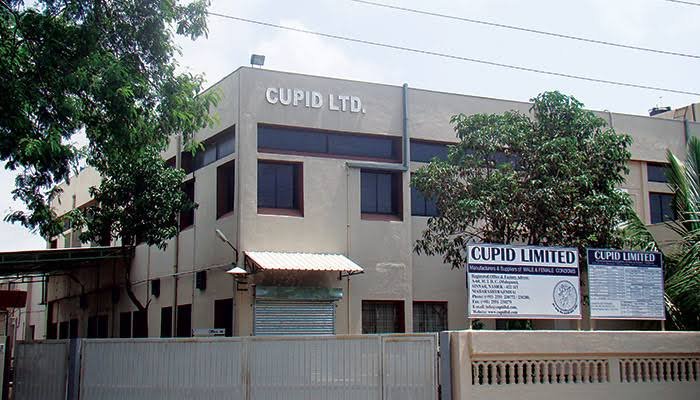
Cupid Limited has delivered extraordinary returns, rising 15,400% in five years and touching a record price of ₹368 on October 9, 2026. The stock gained more than 3% in a single session, adding to its remarkable rally. In 2026 alone, shares have surged 230%, while the one‑year gain stands at 656%. Over shorter periods, the stock has climbed 16% in one week, 30% in one month, 73% in three months, and 292% in six months.
The rally is supported by strong business momentum and upgraded guidance. For FY27, Cupid has raised its revenue target to ₹800 crore and net profit to over ₹250 crore, compared with earlier estimates of ₹725–750 crore and ₹210–225 crore. The company expects Q2FY27 revenue to cross ₹200 crore, driven by institutional orders and private market demand. Expansion in domestic FMCG, healthcare, and personal care segments, along with operational progress at the Palava facility, has strengthened growth prospects.
Global condom industry growth at 8.7% CAGR between FY23 and FY30 is expected to aid Cupid’s international healthcare business. Analysts, however, advise caution, pointing to ₹345 as a crucial support level. Chasing the rally may be risky given the sharp run‑up. The company has also approved conversion of 30 lakh warrants at ₹328.25 per share, adding equity strength.
Cupid’s diversified portfolio and strong order book suggest sustained growth, though investors are urged to monitor valuations carefully.